
The Buyer’s Playbook 🇺🇸 Written for buyers from the United States
How Americans buy
in the Riviera Maya
Almost every American buyer starts with a listing and a town, and a surprising number of them close somewhere else entirely. This is the order that actually works, written by the broker who has watched it go wrong: the money first, then the structure, then the life you intend to live, and only then the property.
You do not need residency
to buy. It works the other way
This is the single most common misunderstanding we hear from American buyers, and it stops people from starting. You do not need a visa, a residency card, an RFC or any Mexican status to own property here. A foreigner on a tourist entry can buy, and does, every week. What you need is a passport, funds you can trace and a fideicomiso, and that is the whole list.
The order that actually helps you is the reverse of what people assume. Buy first, then apply for residency. Owning property here is one of the ways an application is supported, and being an owner with a registered deed, a Mexican bank account and utilities in your name makes the residency conversation far simpler than arriving with nothing. Several of our clients closed on a tourist entry and started their residency afterwards, from a much stronger position.
We start where
everyone else finishes
The typical first email to us contains a link to a condominium in Tulum and a question about rental yield. It is the wrong place to begin, and answering it politely is how buyers end up two months in, emotionally attached to a unit that does not allow their dog, does not allow nightly rental, or sits in a town they will stop enjoying in year three.
So we start at the other end. First the money, because in a cash market the budget does not narrow the search, it decides which towns exist for you at all. Then how you will pay and how you will hold title, because those two change what you are allowed to buy and what you will pay when you sell. Then the life you intend to live here, which is the part nobody puts in an email and the part that eliminates the most inventory. Only then the zone, and last of all the property.
It feels backwards. It is the reason our clients close in forty five to ninety days with a shortlist of three or four instead of a folder of sixty, and the reason so few of them resell within two years.
1. The funds
The real total, including 7 to 10 percent of closing costs. Not the asking price you saw.
2. Structure and payment
Cash, developer financing or a cross border loan, and whose name the trust names.
3. The life
Dog, golf, schools, walkability, guests, long stays. This is what actually rules zones out.
4. Zone, then property
By this point the map has narrowed itself and the shortlist writes itself.
Before the property: which buyer are you?
Here is the part that decides everything and almost nobody is told. Your funds do not just set a price ceiling, they set which market you are allowed to see. There are three buyer profiles in this market and each one opens a different amount of it. Starting with a listing instead of your profile is the original mistake, and every other mistake follows from it.
01 · Full cash
All the capital available up front. This profile sees the entire Mexican market, and that is a much bigger market than the one on the internet.
- Publicly listed properties
- Off market opportunities that are never advertised
- New and older pre construction projects
- Assignment of rights, explained below
- Urgent deals that circulate in private broker chats
- Strategic resales that never appear online
02 · Part cash, part financing
Some of the capital, and a loan for the rest, either from a lender at home or from a Mexican bank. The market shrinks, and not for the reason people expect.
- Down payments in Mexico start around 40 percent for Americans
- A pre qualification is required before you look, and we send you the link
- Not every property qualifies for financing
- The bank has to approve the property, not only you
- Whole developments and whole areas are excluded
- In Tulum many properties, including good investments, are not mortgageable at all
03 · Minimal capital, developer financing
Not enough cash and no traditional financing available. Direct financing from the developer is the only viable route, and it exists, with limits worth knowing before you count on it.
- Very few developers offer it
- The inventory that qualifies is extremely limited
- Pricing is usually higher than the cash price
- Your negotiating power is reduced
- This profile reaches the smallest segment of the market
- It is possible, but the expectations have to be realistic
What an assignment of rights is
A buyer bought very well in pre construction. Before the project is finished or titled, they decide not to continue, so their position is transferred to someone else. It is never published and never marketed, and it is cash only. These are often the best priced opportunities in the market with the most upside left, and they are completely invisible to the public.
Where the real inventory actually is
The listings you can find yourself are the smallest part of this market. Everything else moves person to person: a developer releasing a block before it goes public, an owner who needs to sell this month and does not want a sign on the building, a position in a project changing hands, a broker in Cancún who has a buyer for one of ours and a seller for one of yours.
None of that reaches a portal, because it does not need to. It is already sold by the time it would have been published, which is why access is not a marketing claim here. It is the product.
The reel is not the property
Drone shot, cenote, “only 3 units left”, a price that looks impossible, link in bio. Some of it is real inventory presented well. A lot of it is not, and from a phone the two look identical.
- 01Whether the land was ever ejido
- 02Whether the permits actually exist
- 03Whether the regime allows the rental the caption promises
- 04Who the developer is and what they have delivered before
- 05Whether that is the price, or the price before the mandatory furniture package
- 06Whether the person posting is licensed, or paid per lead and gone after your wire
Instagram is a fine place to find something. It is a terrible place to buy it. So use us as the filter: send the reel, the post, the developer name, the message someone forwarded you. We pull the registry certificate, the permits and the regime, we tell you what the unit next door actually sold for, and we come back with one of three answers.

This market is not on Google, Instagram or Facebook. It moves through licensed brokers, professional associations, private CRMs and broker networks. A licensed Quintana Roo broker, a NAR REALTOR®, and active in AMPI Playa del Carmen and AMPI Cancún. That is the door, and it is the reason you do not start by choosing a property. You start by choosing your buyer’s agent.
Real cases, not hypotheticals
Three American buyers, three questions nobody asked at the beginning. Not stories invented for a brochure.
Those two things fight each other here, and it is the most common internal contradiction we see. Gated communities are inland and you drive out of them; the blocks where you walk to dinner are open streets in the center of Playa del Carmen.
Pick which one you would miss
A buyer arrived asking about Tulum condominiums and mentioned, almost in passing, that he keeps a thirty two foot boat. That one sentence deleted Tulum from the list, because there is no marina.
One sentence, three addresses
Golf does not narrow this coast the way buyers expect, because there are courses from Cancun to Tulum: Playacar, Puerto Cancun, Cancun Country Club, Riviera Cancun, Playa Mujeres, Corasol, Mayakoba, Puerto Aventuras and Tulum Country Club. What actually narrows it is which club you want to play weekly, whether you want frontage or just membership, and what the club costs an owner.
Which club, not whether golf
Notice what all three have in common: the deciding information was cheap and available at the start, and nobody collected it. That is what the questionnaire is for.
Start here. Not with a listing
Everything above explains why. This is where it actually begins: twenty questions, answered once, that tell us your buyer profile, your structure, your lifestyle and your deal breakers. Nothing is sent until you press send, your answers save in your own browser as you go, and it takes about eight minutes. Buyers who fill this out first are the ones who close in the right place.
The discovery questions,
answered online
Nineteen questions, about five minutes. Nothing is sent anywhere until you press the button at the end, and your answers stay in your own browser while you work through them. At the end you get a written read of what your answers point to, and the option to send the summary to us by WhatsApp or email so the first conversation starts from facts instead of guesses.
What type of property are you interested in?
If you are not sure, say so. It is a legitimate answer and it changes how we work with you.
What investment range are you considering?
We ask first because the number decides which towns are real for you, not just which listings. Add 7 to 10 percent of closing costs on top of whatever you pick.
How do you plan to purchase?
This is a cash market. Developer financing exists but only on the developer’s own inventory, and no Mexican bank lends to a non resident on a resale.
How do you expect to hold the title?
No wrong answer, and most buyers pick this after a conversation. It matters early because an LLC adds two to four weeks at the bank.
What is this property mainly for?
The honest answer here rules more inventory in or out than the budget does.
Who is this for?
This changes bedroom count, layout and whole zones, and it is the question that gets skipped most often.
How much of the year will you actually be here?
Be realistic rather than aspirational. Four weeks a year and eight months a year are two completely different purchases.
How close do you want to be to the beach?
Oceanfront roughly doubles the price per square meter against a five minute walk. Both are legitimate, they are just different purchases.
Which of these are true about your life?
Pick everything that applies. Each one of these can eliminate entire zones, and this is the part almost nobody volunteers in a first email.
How will you get around?
A no car plan is the single most restrictive filter on this coast. It rules out almost every gated community, including the best value ones.
Which areas are you considering?
Pick all that apply, including the last two if they are true. Plenty of our buyers have never set foot here, and that is a normal place to start. If this list changes after we talk, that is normal and usually a good sign.
Which of these styles pulls you in?
Pick all that appeal. This is not decoration, it decides which developers and which zones we show you, because each one builds in a different language.
What are your must haves?
Pick all that apply. We treat these as filters, not preferences, so only mark what you would walk away over.
How do you feel about monthly fees?
Amenities are not free. Some buyers want everything included, others want the lowest possible carrying cost, and the two point to different products.
New construction or already built?
Pre construction buys you price and payment terms. Resale buys you certainty, because you can inspect it and read three years of assembly minutes.
How long do you expect to hold it?
Four to eight years is where the math works best here: long enough for the 7 to 10 percent you paid going in to be absorbed by appreciation, short enough to still catch a cycle. Under three is the hardest case.
What is your timeline to buy?
There is no wrong answer. It changes what we send you, not whether we work with you.
Are you already working with another agent here?
If you are, say so. We will not step on another broker’s file, and telling us saves everyone the awkward conversation later.
How would you like us to reach you?
Pick whatever you actually answer, then add your time zone or the hours that work.
Any deal breakers?
Pick every one that would make you walk away, then add anything we missed. Most buyers cannot name these until they see the list, and they are the fastest way for us to stop wasting your time.
Here is what your answers point to
We represent you, not a developer. Nothing in this form is shared with a project, a builder or a portal, and we do not sell leads.
Four ways a foreigner
can own here
This is the question that arrives most often and gets answered worst. Everything within fifty kilometers of the coast and one hundred kilometers of a land border is the restricted zone, and no foreign individual takes a direct deed inside it. That does not mean you cannot own. It means the ownership sits in one of four structures, and the right one depends on whether you are buying a home, a rental, or an asset you intend to pass on.
Fideicomiso in your own name
You are the owner. A Mexican bank is named on the deed as trustee for fifty years, renewable indefinitely, and you are named in the trust as the owner of the property, with the full right to use it, remodel it, rent it, sell it and leave it to your heirs. The bank administers the instrument, it does not own your home and it cannot use, encumber or sell it. The legal term is fideicomisario, which translates badly into English as beneficiary and makes buyers think they are second in line. They are not. This is what the overwhelming majority of foreign buyers on this coast actually have.
Right for you if
- One or two names on a home or second home
- Approved by the bank in days, not weeks
- Keeps the primary residence exemption on capital gains if you become a tax resident
- Cheapest to set up and to keep
- Heirs can be named as substitute beneficiaries in the trust itself
What it costs you
- No liability separation between you and the asset
- Adding or removing a person later means amending the trust
- Not the right vehicle for several partners
- If you die without naming substitutes, the estate goes through a Mexican process
USD 1,000 to 2,000 at closingThen USD 550 to 900 a year in bank fees
Single member company in the fideicomiso
The same structure with one member, which is the version most individual foreign buyers use. Often disregarded for US federal tax purposes, so the income and the reporting flow to your personal return rather than to a separate corporate one.
Right for you if
- The liability shield without a partnership return
- Simple US reporting for most single owners
- Same routine acceptance by the trust bank
- Clean path to add a member or a manager later
- Works well when the buyer already has an LLC for other assets
What it costs you
- Same loss of the residence exemption as any company owner
- Same apostille delay at the bank
- Still an annual state filing and registered agent cost
- No advantage at all if the property is purely a personal home you will live in
Trust cost plus a few hundred dollarsThen trust fees plus the state annual report
Owning through a US LLC
The same bank trust, but the owner named in it is your company rather than you personally. When the property changes hands later, what moves is the membership interest, not a Mexican deed. This is the structure Grace was asking about, and it is routine here.
Right for you if
- Liability separation between the asset and you
- Several partners without amending the trust each time
- Transfer by assigning membership interest, no new deed
- Estate planning through the operating agreement
- Accepted by Mexican banks and notaries as a matter of routine
What it costs you
- Does not replace the fideicomiso, it sits inside it
- Gives up the primary residence exemption on capital gains
- Needs apostilled formation documents, add two to four weeks
- Annual LLC maintenance and US filings on top of the trust
- Rental income is still taxable in Mexico, with an RFC and monthly filings
Trust cost plus company formationThen trust fees, plus state LLC fees and US filings
Mexican company
A Mexican corporation takes the deed directly, with no trust at all. It is the only structure with no fideicomiso, and the trade is real bookkeeping: it must have a genuine business purpose, and the tax authority treats it as an operating business rather than a holding shell.
Right for you if
- No fideicomiso and no annual bank fee
- Deeds the property directly, including outside the restricted zone
- Deducts real operating expenses against rental income
- The right answer for commercial property or several units
- Scales to an actual rental operation rather than one unit
What it costs you
- Requires a genuine business purpose, not a workaround
- Monthly accounting, an RFC and a Mexican accountant, permanently
- Distributing profit to a foreign shareholder has its own tax treatment
- Wrong and expensive for a single personal residence
- More expensive to run than any trust, even though it is cheaper to hold
Formation plus accounting setupThen a monthly accountant and permanent filings
General guidance and not tax or legal advice. The structure has consequences on the way out as well as the way in, particularly for capital gains and for the residency exemption, so it should be chosen with your accountant and a Mexican notary before the offer, not after. We will tell you plainly when your case does not need the complexity.
Inside the fideicomiso: what actually differs
Options 01, 02 and 03 above are three ways to be the named owner inside the same bank trust. Option 04, the Mexican company, is the only route with no fideicomiso and is not in this table. Find the row you care about and read across.
| What changes | 01 · Your own name | 02 · Single member company | 03 · LLC with partners |
|---|---|---|---|
| Who owns the property | You, named in the trust | Your company, named in the trust | Your company, named in the trust |
| Capital gains on exit | Exemption possible if you are a tax resident and it is your home | No exemption | No exemption |
| Liability separation | None, the asset and you are the same | Yes | Yes |
| Bank approval | Days | Two to four extra weeks, apostilled documents | Two to four extra weeks, apostilled documents |
| Adding or removing people | Amend the trust each time | Not applicable, one member | Assign membership, no trust amendment |
| Passing it on | Substitute owner named in the trust | Operating agreement | Operating agreement |
| Annual admin | Trust fee only | Trust fee plus one state filing | Trust fee, state filing and a partnership return |
| Tax on Mexican rent | Identical in all three. Taxable in Mexico, needs an RFC and monthly filings. The structure moves the rate and the deductions, never the obligation | ||
| If the title is defective | Identical in all three. The bank will not issue the trust and the notary will not sign, so the purchase stops. No structure carries a bad title through | ||
Choose this with your accountant and a Mexican notary before the offer, not after. The consequences land on the way out, not the way in, and we will tell you plainly when your case does not need the complexity.
The advantage nobody sells you
With a fideicomiso in the middle you get a second review for free. Before the trust bank will accept the property it checks the title chain, the registry certificate, the appraisal, the seller identity, the source of funds and, on pre construction, the developer and the project. The bank is putting its own name on the deed, so it has every reason to be strict, and it can refuse a project outright. Buyers who try to avoid the trust to save the fee give that up.
The misunderstanding to kill first
A company does not let you skip the fideicomiso inside the restricted zone. It sits inside it, as the named owner. Anyone telling you otherwise is describing a Mexican company, which is option 04 and a different animal. And the term itself confuses people: the legal word is fideicomisario, which translates badly into English as beneficiary and makes buyers think they are second in line. You are the owner.
Yes, you can buy here
with a 401k or a self directed IRA
This is the one funding route almost no American buyer knows about until we mention it, and it is legitimate. A self directed IRA or a solo 401k can hold foreign real estate, which means a property in Quintana Roo can sit inside the account rather than being bought with taxed savings. It is not a loophole and it is not for everyone, because the rules are strict and breaking them is expensive. It is specific to the United States, and it is one of the few genuine advantages an American buyer has here that nobody uses.
- The account must be with a self directed custodian, not a standard brokerage
- The property is owned by the retirement account, not by you personally
- You cannot use the property yourself while it is held this way
- Rental income flows back into the account, tax deferred or tax free depending on the account
- All expenses have to be paid by the account, never out of pocket
- The fideicomiso still applies, with the account named as owner
>
A dedicated page comparing these four structures in depth is coming next. If your case is urgent, tell us the shape of it and we will walk you through it with our notary.
Same budget,
completely different map
This is the section that does not exist anywhere else, and it is the one that saves the most time. Take one buyer, one number, and change a single fact about how they live. The list of viable addresses changes entirely.
Whole categories of rental focused condominium disappear, because many regimes in the tourist corridors prohibit pets or cap them by weight, and the highest turnover buildings are the strictest.
Courses run the whole coast, so the filter is not golf, it is which club and whether you want frontage. Corasol and Grand Coral are the same development under two names, which trips up a lot of buyers reading listings.
The school run becomes the deciding constraint, and it points north of Tulum. Bilingual and international schools cluster around Playa del Carmen and Cancún.
This is the most restrictive filter of all and it eliminates almost every gated community, including the ones with the best value.
Now the regime matters more than the view. A building that does not permit short term rental makes the entire projection void, and that is most of the hotel zone and most consolidated residential communities.
Diving is not evenly distributed. Serious divers end up in Cozumel, and buyers who want flat fresh water rather than surf end up on a lagoon, which is a completely different product at a completely different price.
The opposite profile, and the one that gets the most house for the money because it is not competing with rental buyers for the same product.
None of these lists is a recommendation. They are what the map looks like once one fact about your life is known, which is why we collect those facts before we send you a single listing.
See what USD 500,000 buys today in Playa del Carmen, Tulum, Puerto Morelos and Cancún.
The five questions
every buyer sends us
Legal process, rental potential, appreciation, HOA fees and clean title. They arrive in almost exactly that order, in almost exactly those words. Here is each one answered in a single line, then the numbers we actually see, then the one thing that goes wrong most often.
The notary is a public official, not a lawyer you hire, and the deed is only yours once it is registered.
- Offer accepted, then a promissory contract with the deposit in escrow
- Due diligence: registry certificate, cadastral record, no debt certificates, regime and assembly minutes
- Fideicomiso permit from Foreign Affairs and bank approval of the trust
- Signing before a notario público, in person or by power of attorney
- Registration of the deed, which is what makes it yours against the world
Add two to four weeks if you buy in an LLC, because the formation documents have to be apostilled.
Realistic, but only if the regime allows it and you underwrite the net instead of the gross.
- Net runs 3 to 10 percent depending on the zone and the microzone, and the spread inside one town is bigger than the spread between towns
- 5 to 8 percent gross is typical in the strong corridors
- Management takes 18 to 25 percent, or 30 plus with a hotel style program
- We hand ours to Playa Moments, our vacation rental and property management team
- Nightly rental is decided by the condominium regime, not by the town
- Mexican tax, an RFC and monthly filings are not optional
- Long term rental to residents is steadier and is what many owners end up doing
The one that kills projections: buying in a building whose regime does not permit short term rental. Most of the Cancún hotel zone does not. Once you own, Playa Moments runs the rental and the property for you, so the number you underwrote is the number someone is accountable for.
There is no single number for the Riviera Maya. It is a zone by zone question, and the spread between zones is enormous.
- Cancún has run around 25 percent in recent years, driven by supply limits and the airport
- The established corridors sit closer to 6 to 10 percent a year in dollars
- It moves with the cycle and with regulation, so any number has a date attached to it
- Scarcity of buildable land inside a finished community
- Infrastructure that is built, not announced
- Four to eight years absorbs the entry costs and still catches the cycle
A developer projection is a marketing document, not a forecast. Ask what was delivered on the last phase instead.
Called cuotas, set by the condominium assembly, and we pull the documents behind them so you do not have to.
- Considerably less in a simple low rise, and zero in some house neighborhoods
- Extraordinary assessments are voted by the assembly and are binding on you
- Ask whether a reserve fund exists or whether every repair is a special call
- Unpaid fees follow the property, so a no debt certificate is mandatory
You do not have to chase this. We request the statements, the assembly records and the no debt certificate as part of the offer, and we tell you in one sentence what they say.
You do not need to hire what you would hire at home. Here the notary does that work, and it is his legal responsibility.
- In the United States you buy title insurance and hire a closing attorney. Neither is the mechanism here
- The notario público is a public official who verifies title, calculates taxes and is liable for the deed
- He pulls the certificado de libertad de gravamen, the cadastral record and the no debt certificates
- On a condominium we read the regime and three years of assembly minutes ourselves
- Title insurance exists in Mexico and it is optional. On a registered condominium it is usually unnecessary, and it gets sold hard to foreign buyers precisely because it sounds familiar. In the United States you buy it because there is no public official verifying the chain of title. Here the notary does that work, it is his legal responsibility, and inside the restricted zone the trust bank reviews the file again. You are paying twice for a check that already happened
- Ejido land that was never regularized cannot be cleaned with paperwork, and that is the exception that matters
Where you do want a specialist: raw land in Tulum and Costa Mujeres, where ejido history is common. We have attorneys who work only those zones, and we bring them in there. Read what that looks like in the Isla Blanca guide.
Yes, it works and it is routine. It sits inside the fideicomiso, it does not replace it.
- Your company is named as the owner in the trust, the bank holds the deed only as trustee
- Accepted by Mexican banks and notaries as a matter of routine
- Good for liability, partners and estate planning
- Needs apostilled formation documents
- Does not change the obligation to pay Mexican tax on rent
The tradeoff: a company owner gives up the primary residence exemption on capital gains. If you might live here one day, say so first.
Do I need residency or a visa to buy in Mexico?
No, and this is the most common misunderstanding we hear. A foreigner on a tourist entry can buy property in Mexico, and it happens every week. What you need is a passport, funds you can trace and, inside the restricted coastal zone, a fideicomiso. No visa, no residency card and no RFC is required to purchase, although you will need an RFC if you rent the property out. In practice the order runs the other way: buy first, then apply for residency, because owning property here supports an application and an owner with a registered deed, a Mexican bank account and utilities in their name is in a much stronger position than an applicant with nothing.
Can a foreigner buy property in Mexico in an LLC?
Yes, and it is common. Inside the restricted coastal zone the title itself is held in a fideicomiso, a renewable bank trust, and your US company is named in that trust as the owner of the property, with the bank on the deed only as trustee. It works, it is accepted by the banks and the notaries, and it is often the right answer for liability and estate planning. What it does not do is remove the fideicomiso or its annual fee. Outside the restricted zone a Mexican company can hold the deed directly, which is a different structure with different bookkeeping.
What is a clean title in Mexico and how do you verify it?
Clean title means the property is registered in the seller’s name at the Registro Público de la Propiedad, free of liens and encumbrances, current on property tax and water, and in the case of a condominium current on its maintenance fees with the regime properly constituted. It is verified with documents, not assurances: a certificado de libertad de gravamen, the cadastral record, a certificate of no debt from the municipality and the water utility, the condominium regime and the last three years of assembly minutes, plus a survey where the boundaries matter. Ejido land that was never regularized cannot be verified this way, and that is the single most common way foreign buyers lose money here.
Why do you ask about my budget before showing me properties?
Because in this market the budget does not narrow the search, it defines which towns exist for you. Two hundred thousand dollars is a good two bedroom in the right building and it is nothing at all in Mayakoba. Asking first is not a sales tactic, it is the only way to avoid showing you three weeks of properties you will not buy, and it lets us tell you honestly when the number does not match the goal so you can decide whether to adjust the number or the goal.
What rental income is realistic in the Riviera Maya?
It depends far more on the building than on the town. A well located two bedroom with a rental program can run 55 to 70 percent annual occupancy in Playa del Carmen and Tulum, which lands most owners in the 5 to 8 percent gross range before management, fees, tax and vacancy. Net is typically 3 to 5. Two things break those numbers: buying in a building whose regime does not allow nightly rental, which is most of Cancún’s hotel zone and most consolidated residential communities, and assuming the developer’s projection is a forecast rather than a marketing document.
How much does appreciation really run here?
Over the last decade the strong corridors have averaged roughly 6 to 10 percent a year in dollar terms, with the peaks in areas that received real infrastructure rather than the ones with the most advertising. Appreciation here is driven by three things you can actually check before you buy: scarcity of buildable land inside a finished community, infrastructure that is built rather than announced, and demand that is not purely seasonal. Anything sold to you on a projection alone is a bet, not a plan.
How do HOA fees work in Mexico?
They are called cuotas de mantenimiento and they are set by the condominium assembly under the regime, not by a management company. Expect roughly 2.50 to 4.50 US dollars per square meter per month in a full amenity building, less in a simple low rise, and nothing at all in some house neighborhoods on municipal streets. The number to ask for is not this month’s fee, it is the last three years of assembly minutes, because that shows how often extraordinary assessments have been called and whether the reserve fund actually exists.
Do I need to be in Mexico to close?
No. Most of our clients close with a power of attorney granted before a Mexican consulate or an apostilled US power of attorney, and the notary signs on their behalf. You do need to be identifiable and compliant: passport, proof of address, RFC in some cases, and clean source of funds documentation. Being remote is normal here, being unrepresented is what causes problems.
Can I bring my dog?
You can bring it into the country easily. Getting it into the building is the harder part, and it is a real reason buyers change zones. Many condominium regimes in the tourist corridors either prohibit pets or cap them by weight, and a rental focused building with heavy turnover is usually the strictest. Residential communities are the opposite: houses with their own garden, pet parks and no weight limits. This one question can eliminate half a shortlist, which is exactly why we ask it before we send listings.
Ready to go deeper? The closing guide covers the process document by document, and the buyer FAQ answers the rest.
Every photograph on
this page is a real house
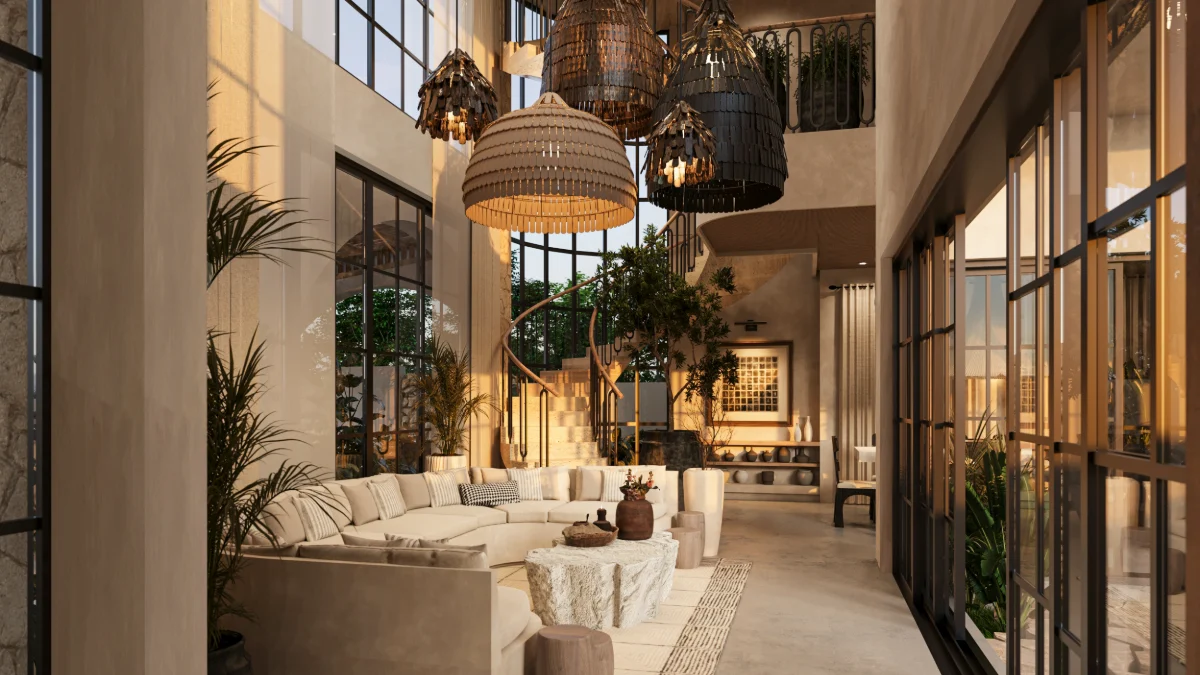
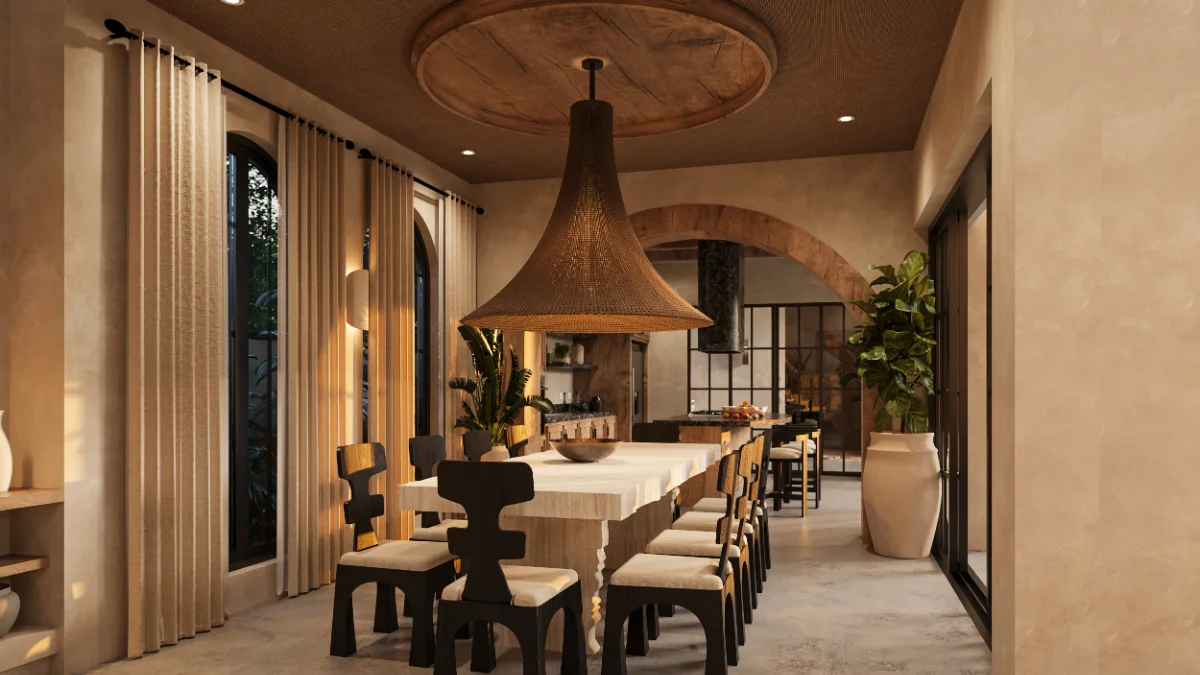
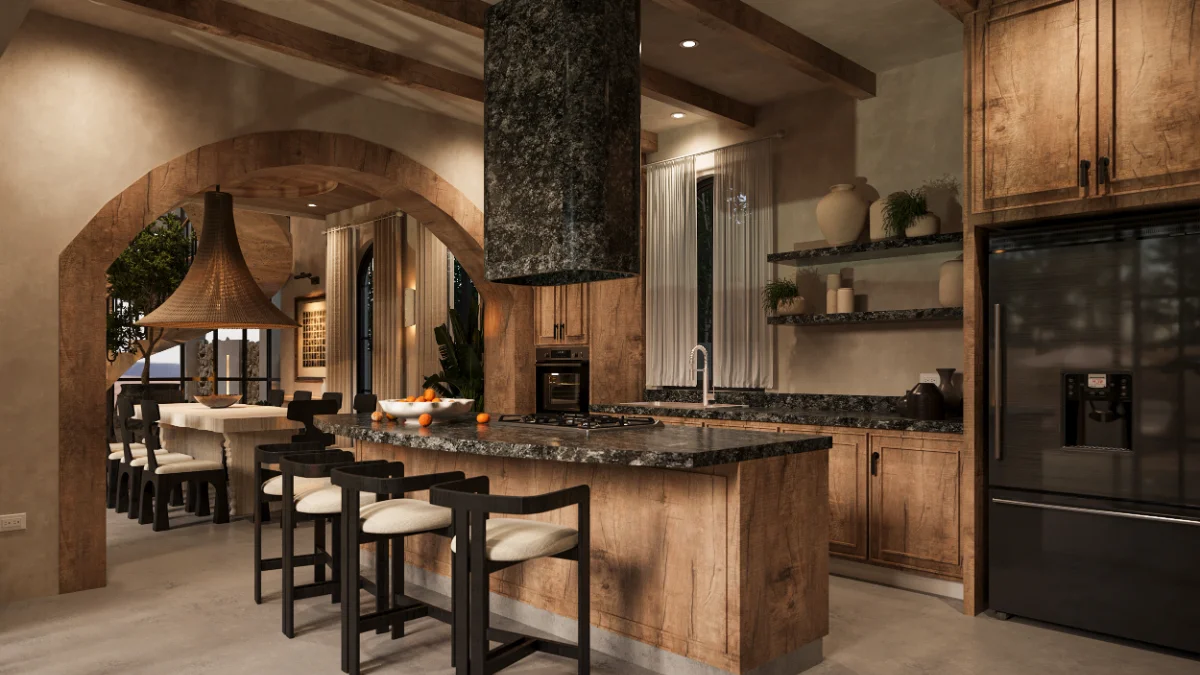
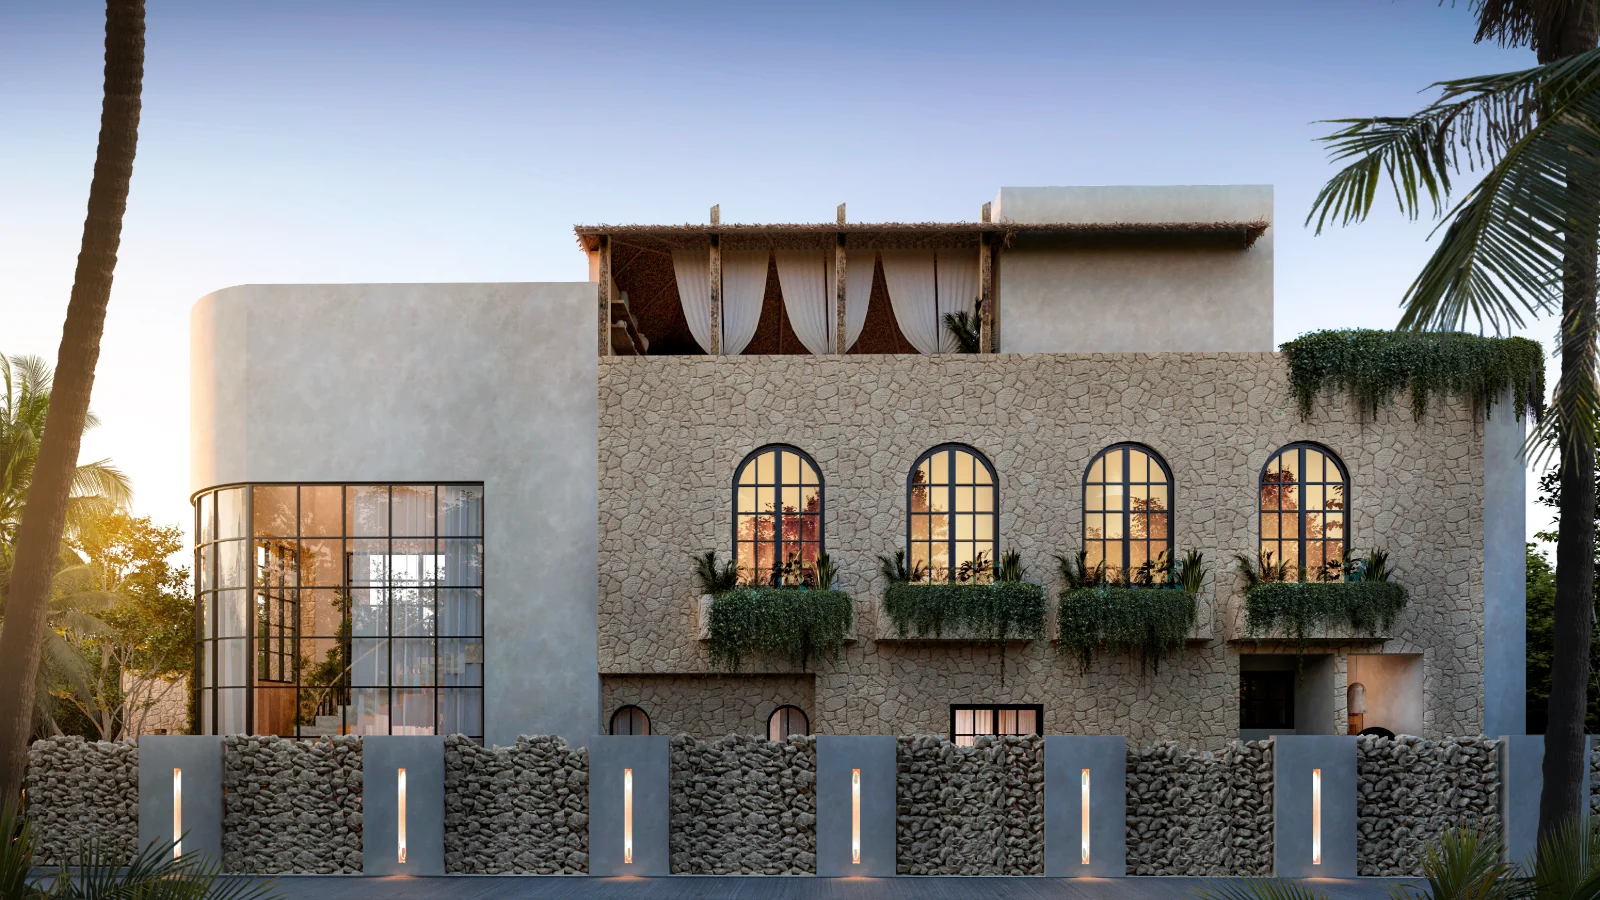
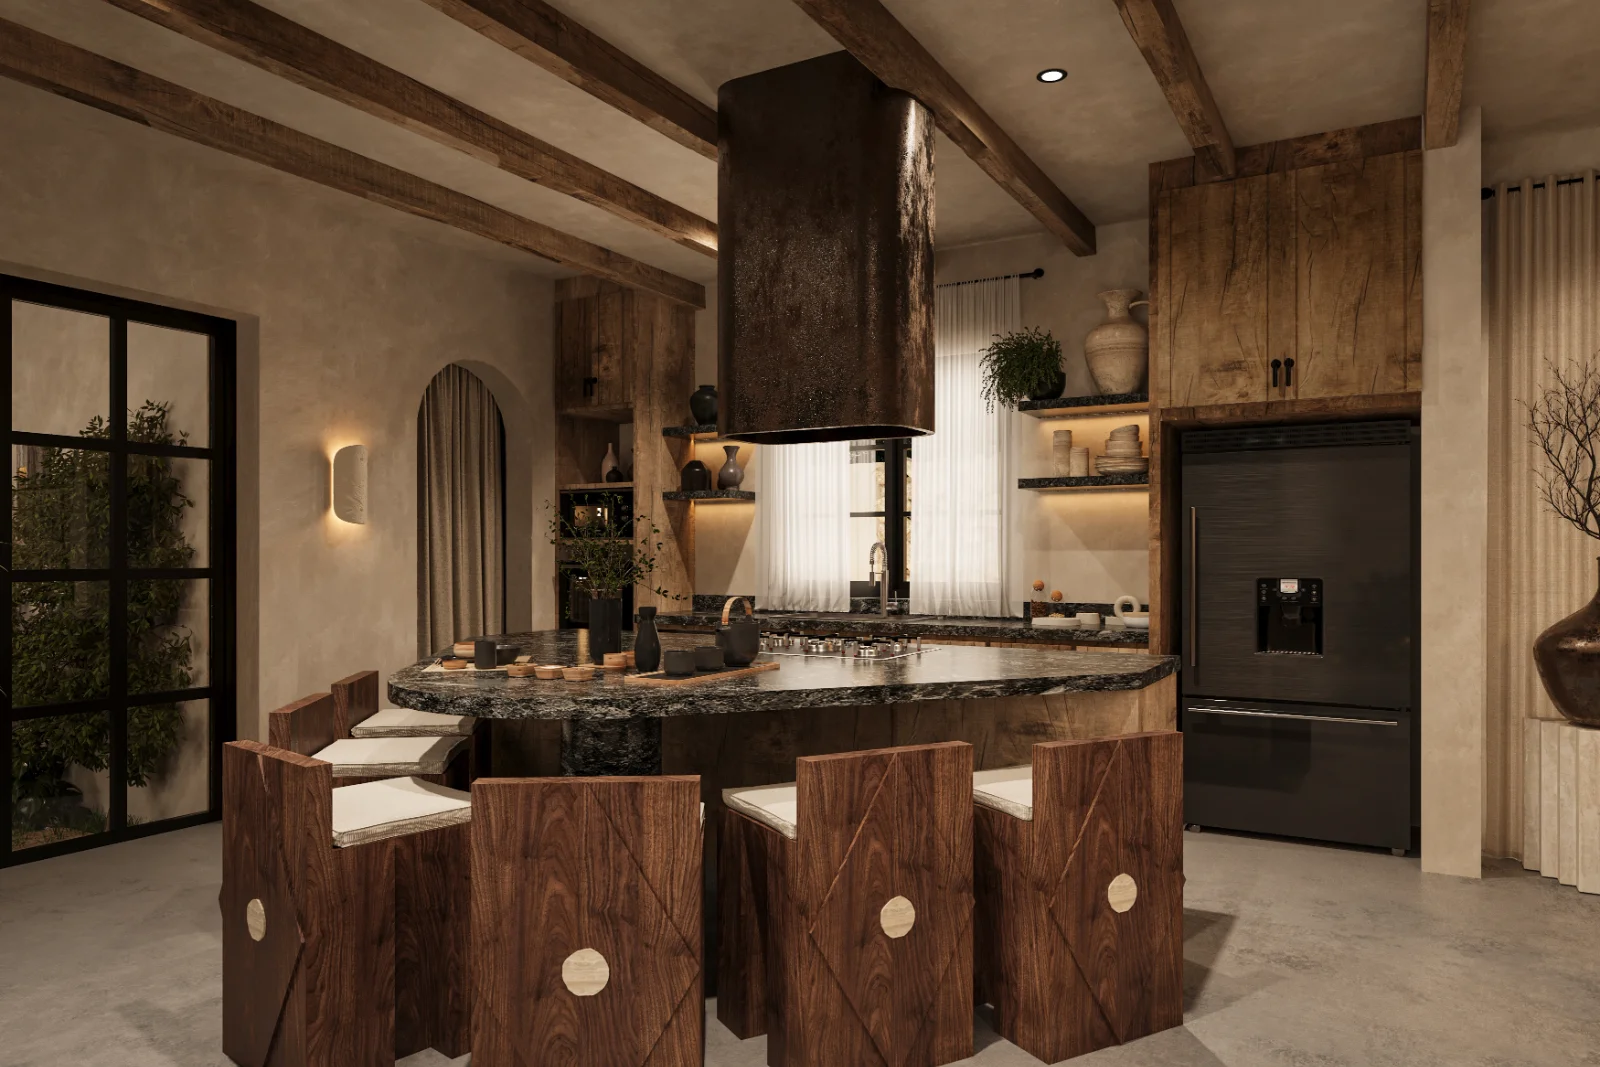
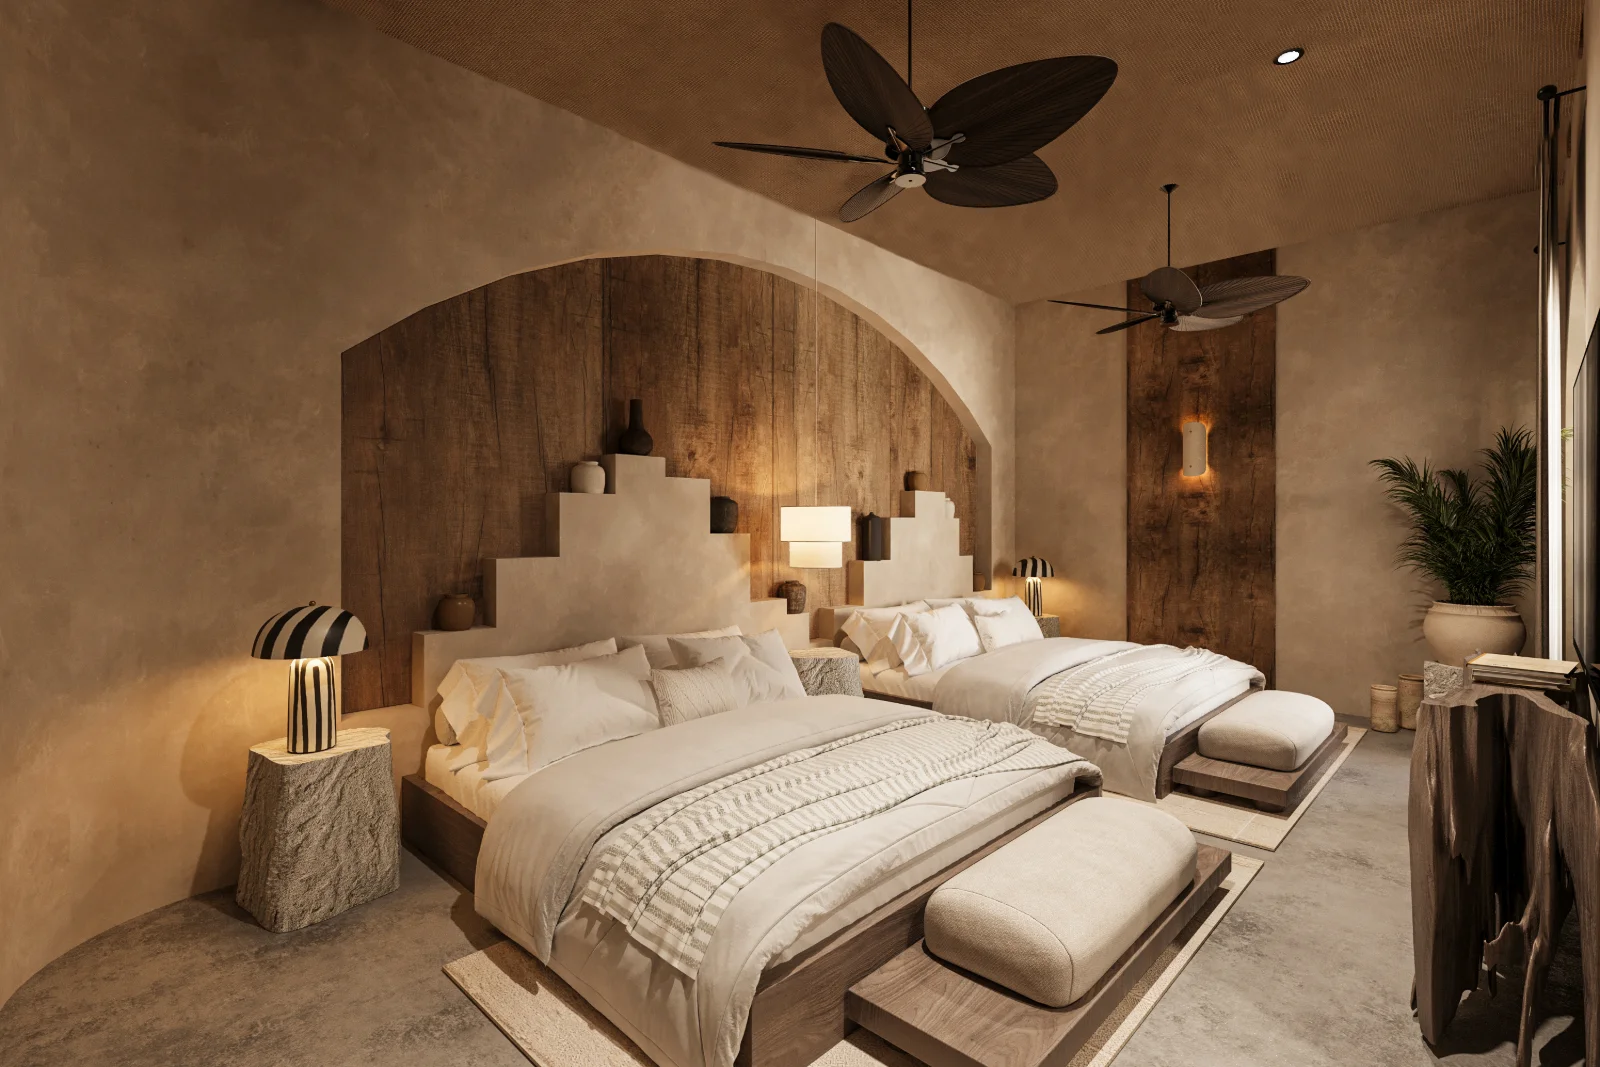
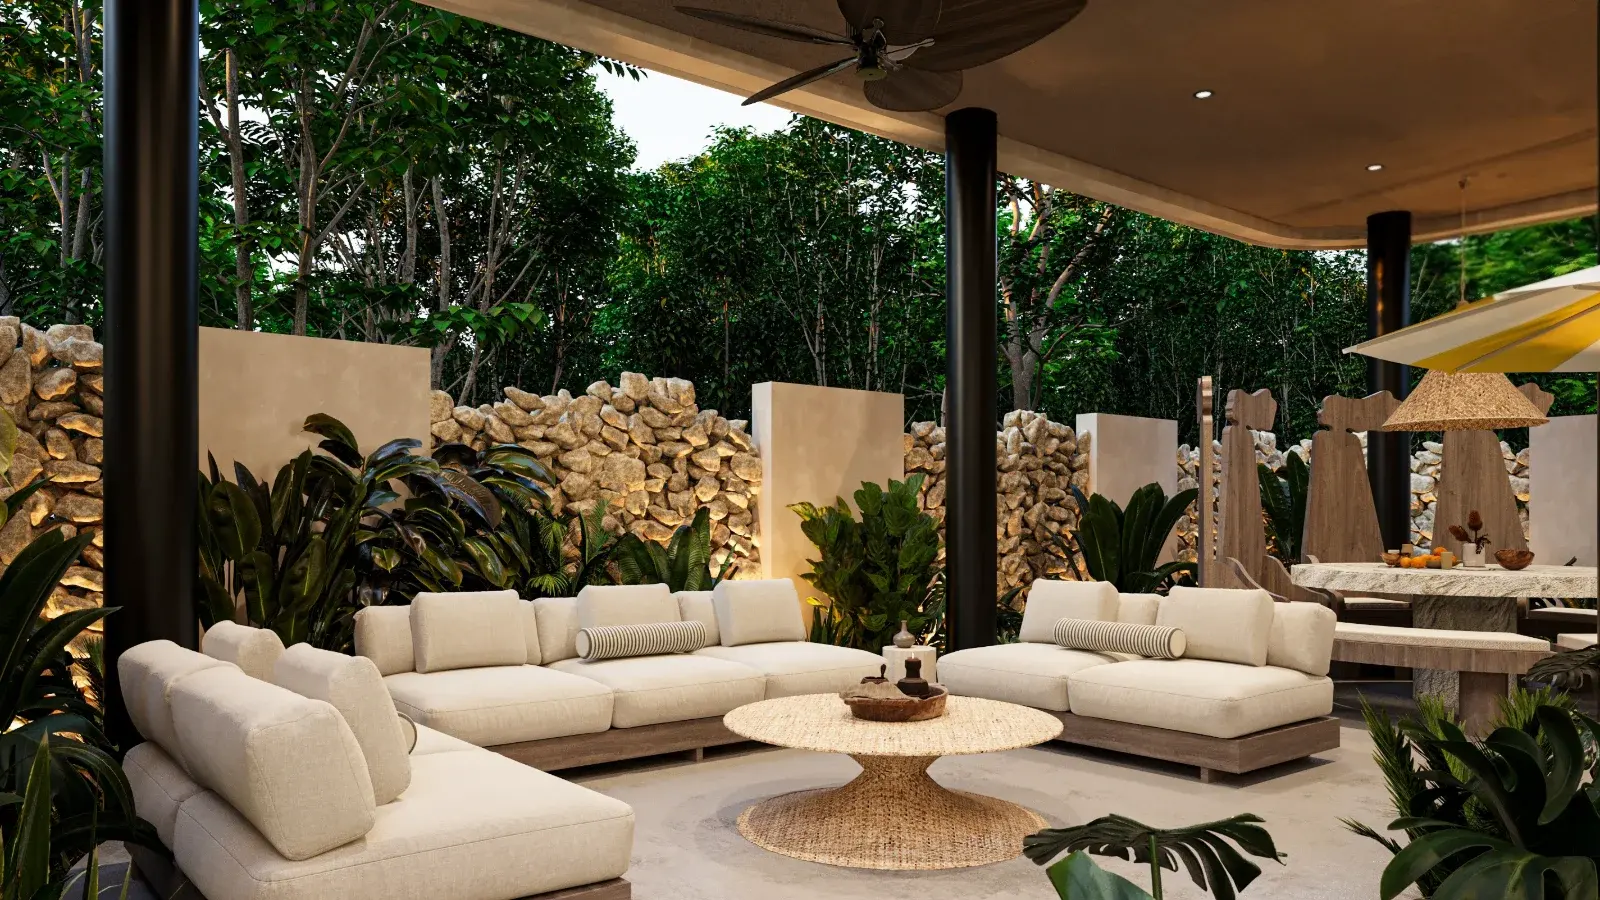
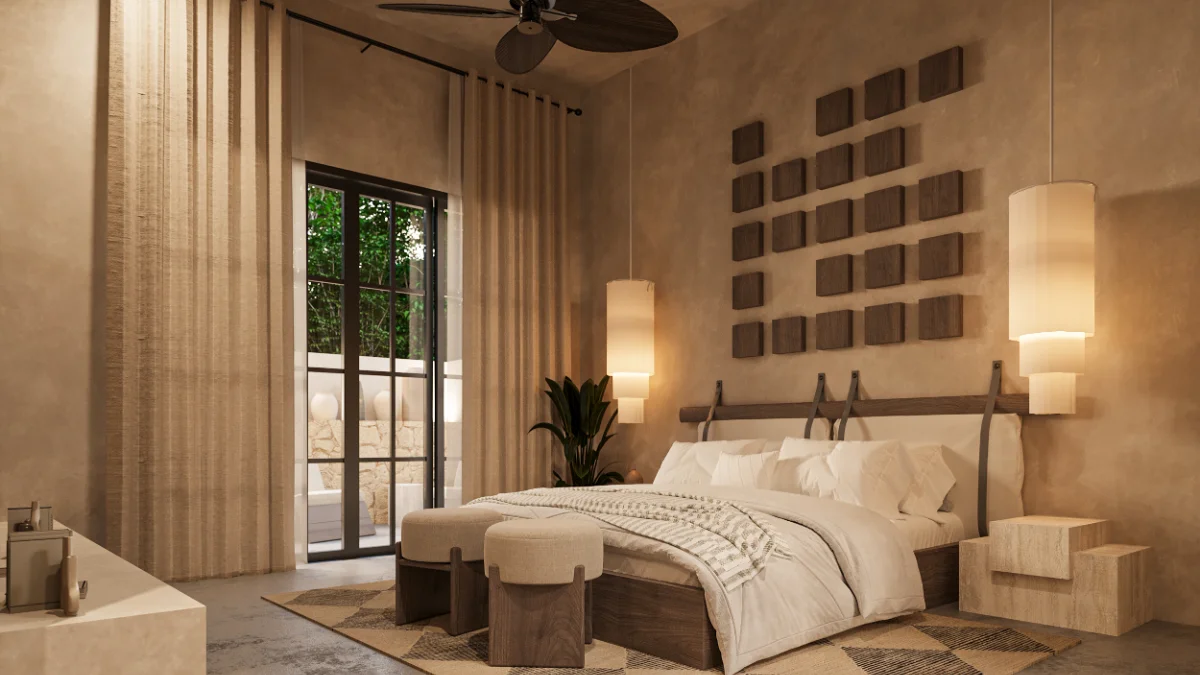
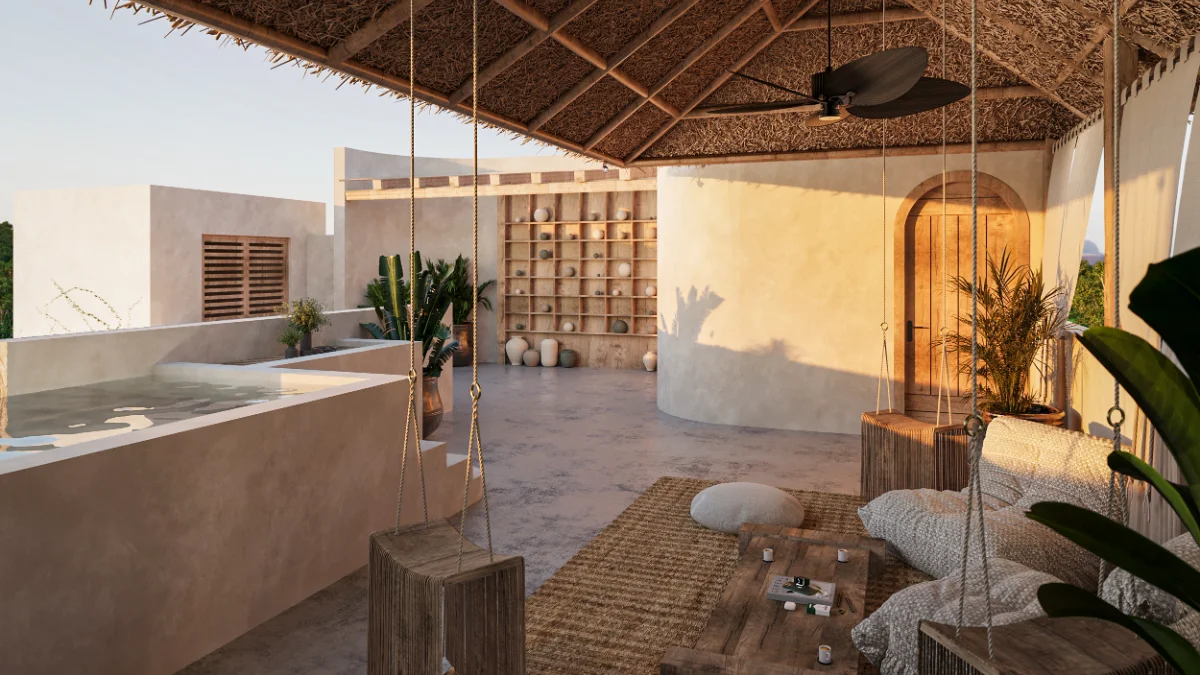
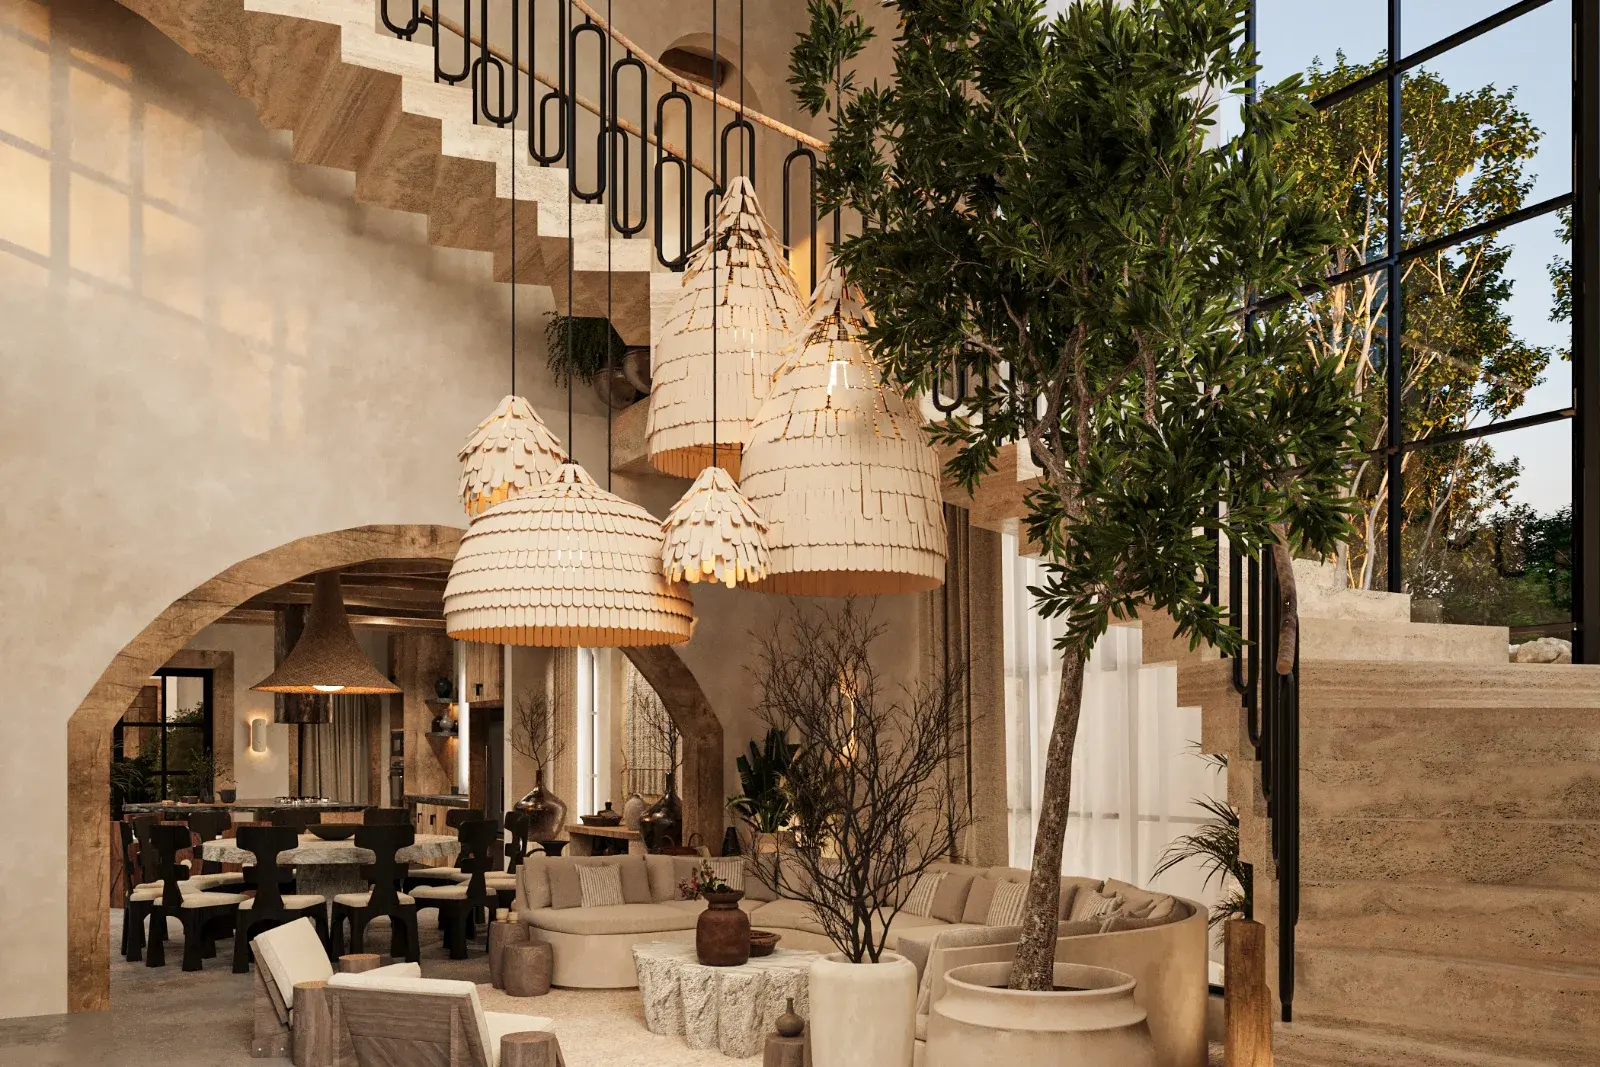
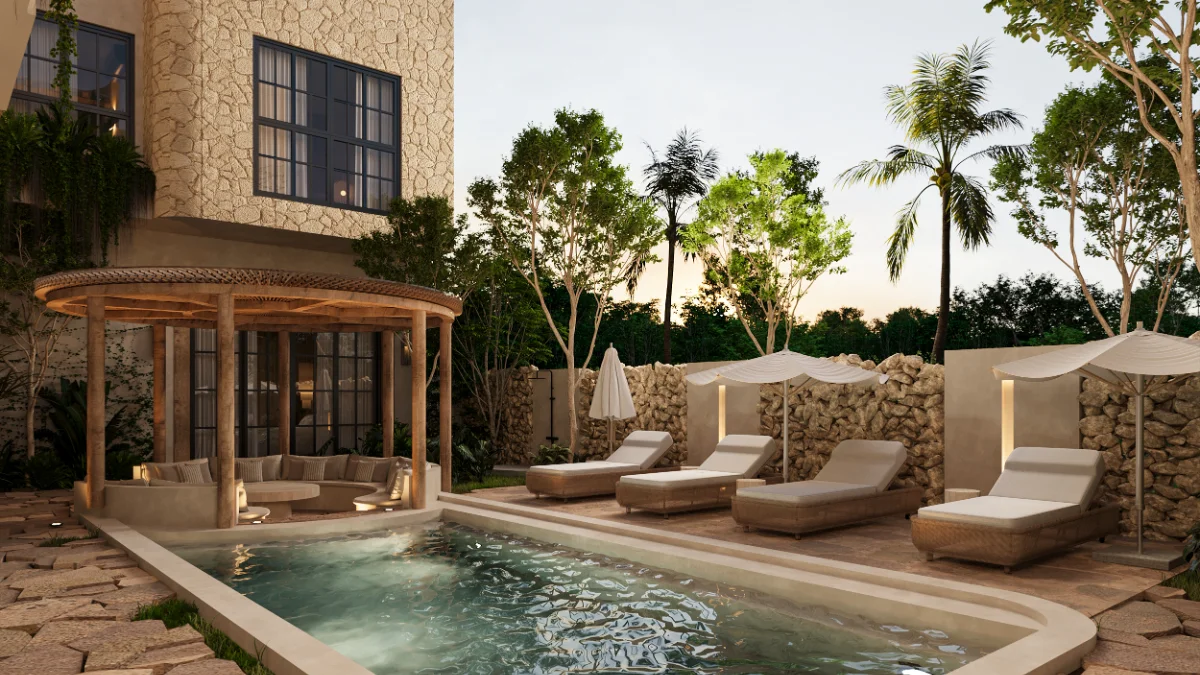
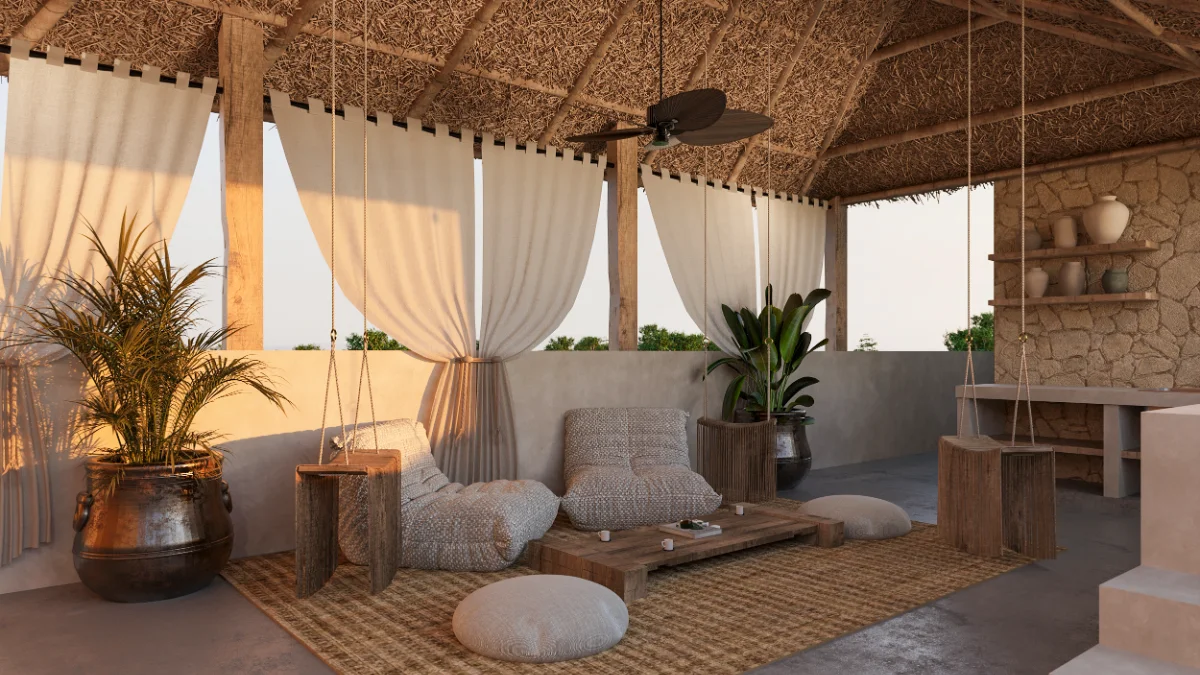
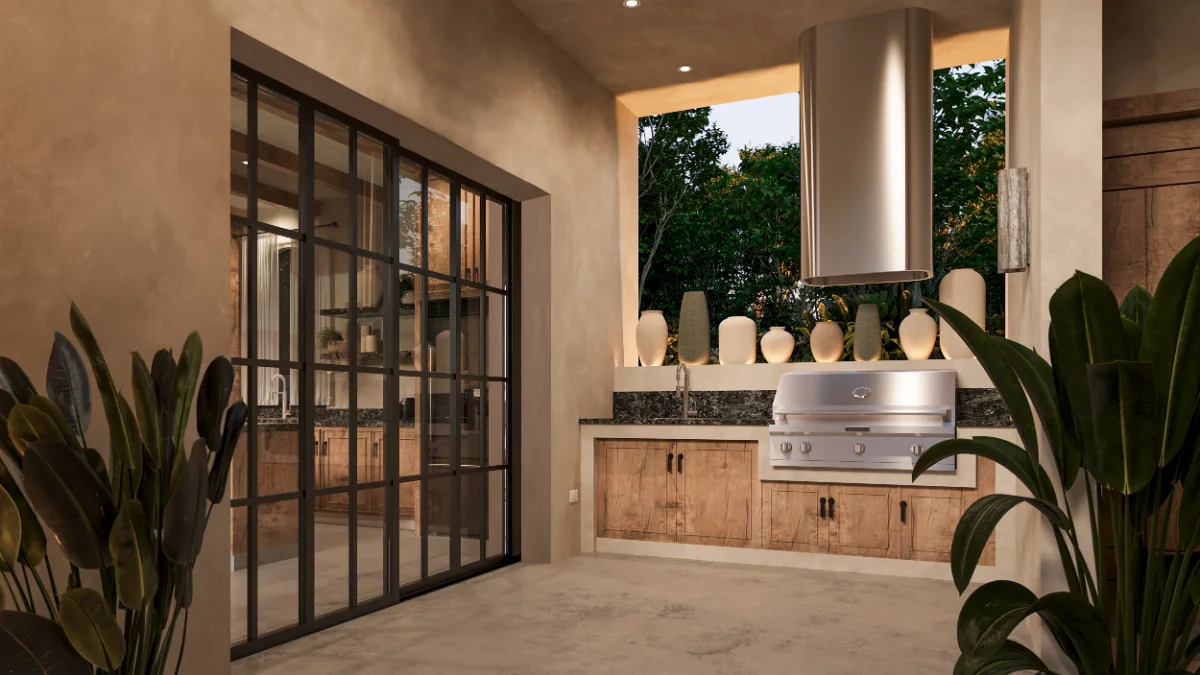
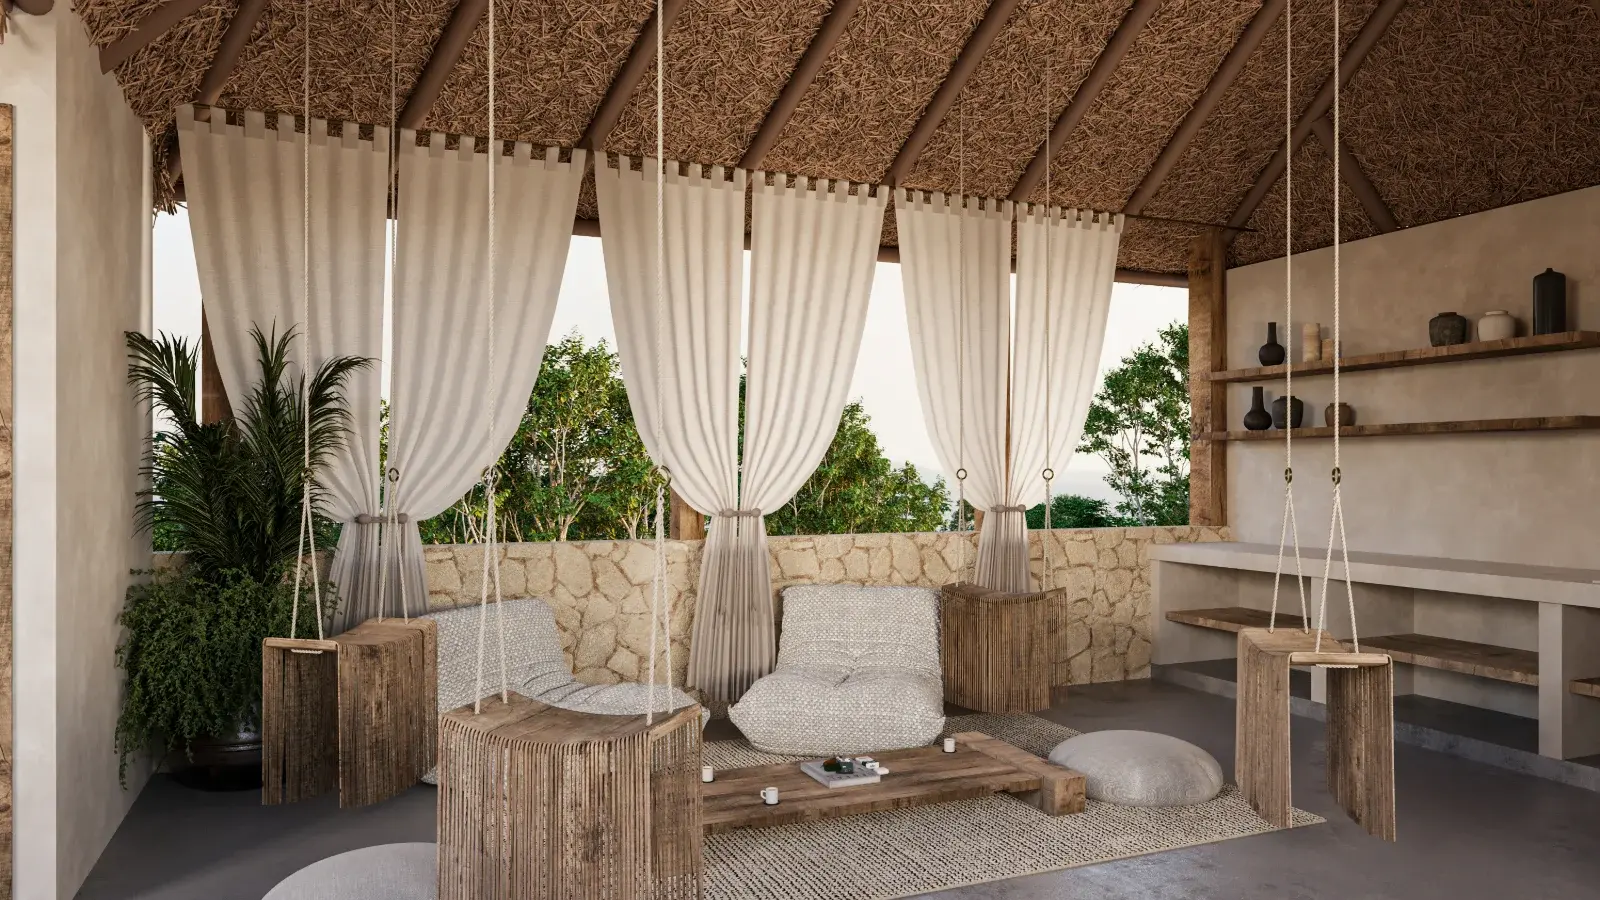
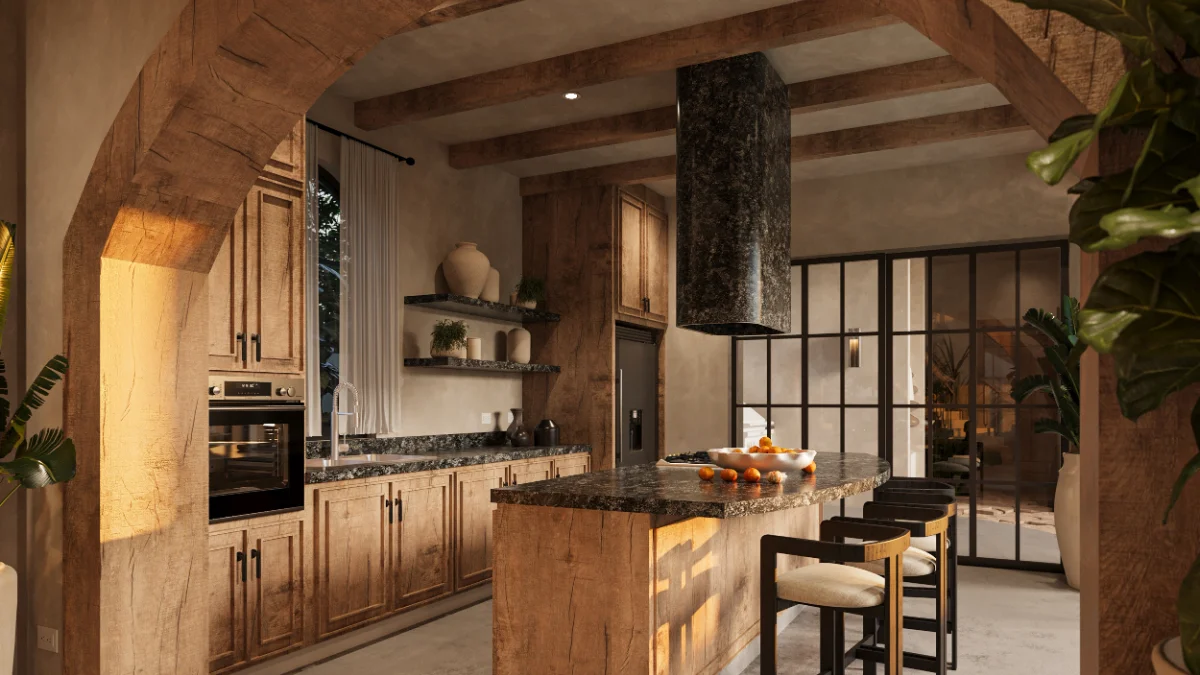
Nothing here is a stock image, a mood board or a render borrowed from another country. These are homes in the Riviera Maya: the double height living room at the top, the timber arch kitchen, the rooftop palapa with the swing seats, the pool at dusk. They were photographed here, and houses like them are for sale here right now.
That is the whole point of the questionnaire above. Buyers assume this level of design belongs to a resort or to a budget they do not have. Very often it does not. It belongs to a specific developer, in a specific zone, at a price that surprises people, and the only way we can point you at it is if we know what you actually want.

Start with the questions,
not the listings
Answer the twenty questions above and send us the summary, or just tell us the shape of your situation. We will tell you which zones are actually viable for your number and your life, what structure your case needs, and where the honest tradeoff is. We represent you, not a developer, and we will say so when the answer is that you should wait.
